Orange County Retail Q3 2026: Tight Space, Pickier Capital
By Jim Resha
Senior Vice President, Sperry Commercial | The Resha Group
National Chair, Sperry National Retail Group
Orange County Retail in Q3 2026: The Market Split in Two
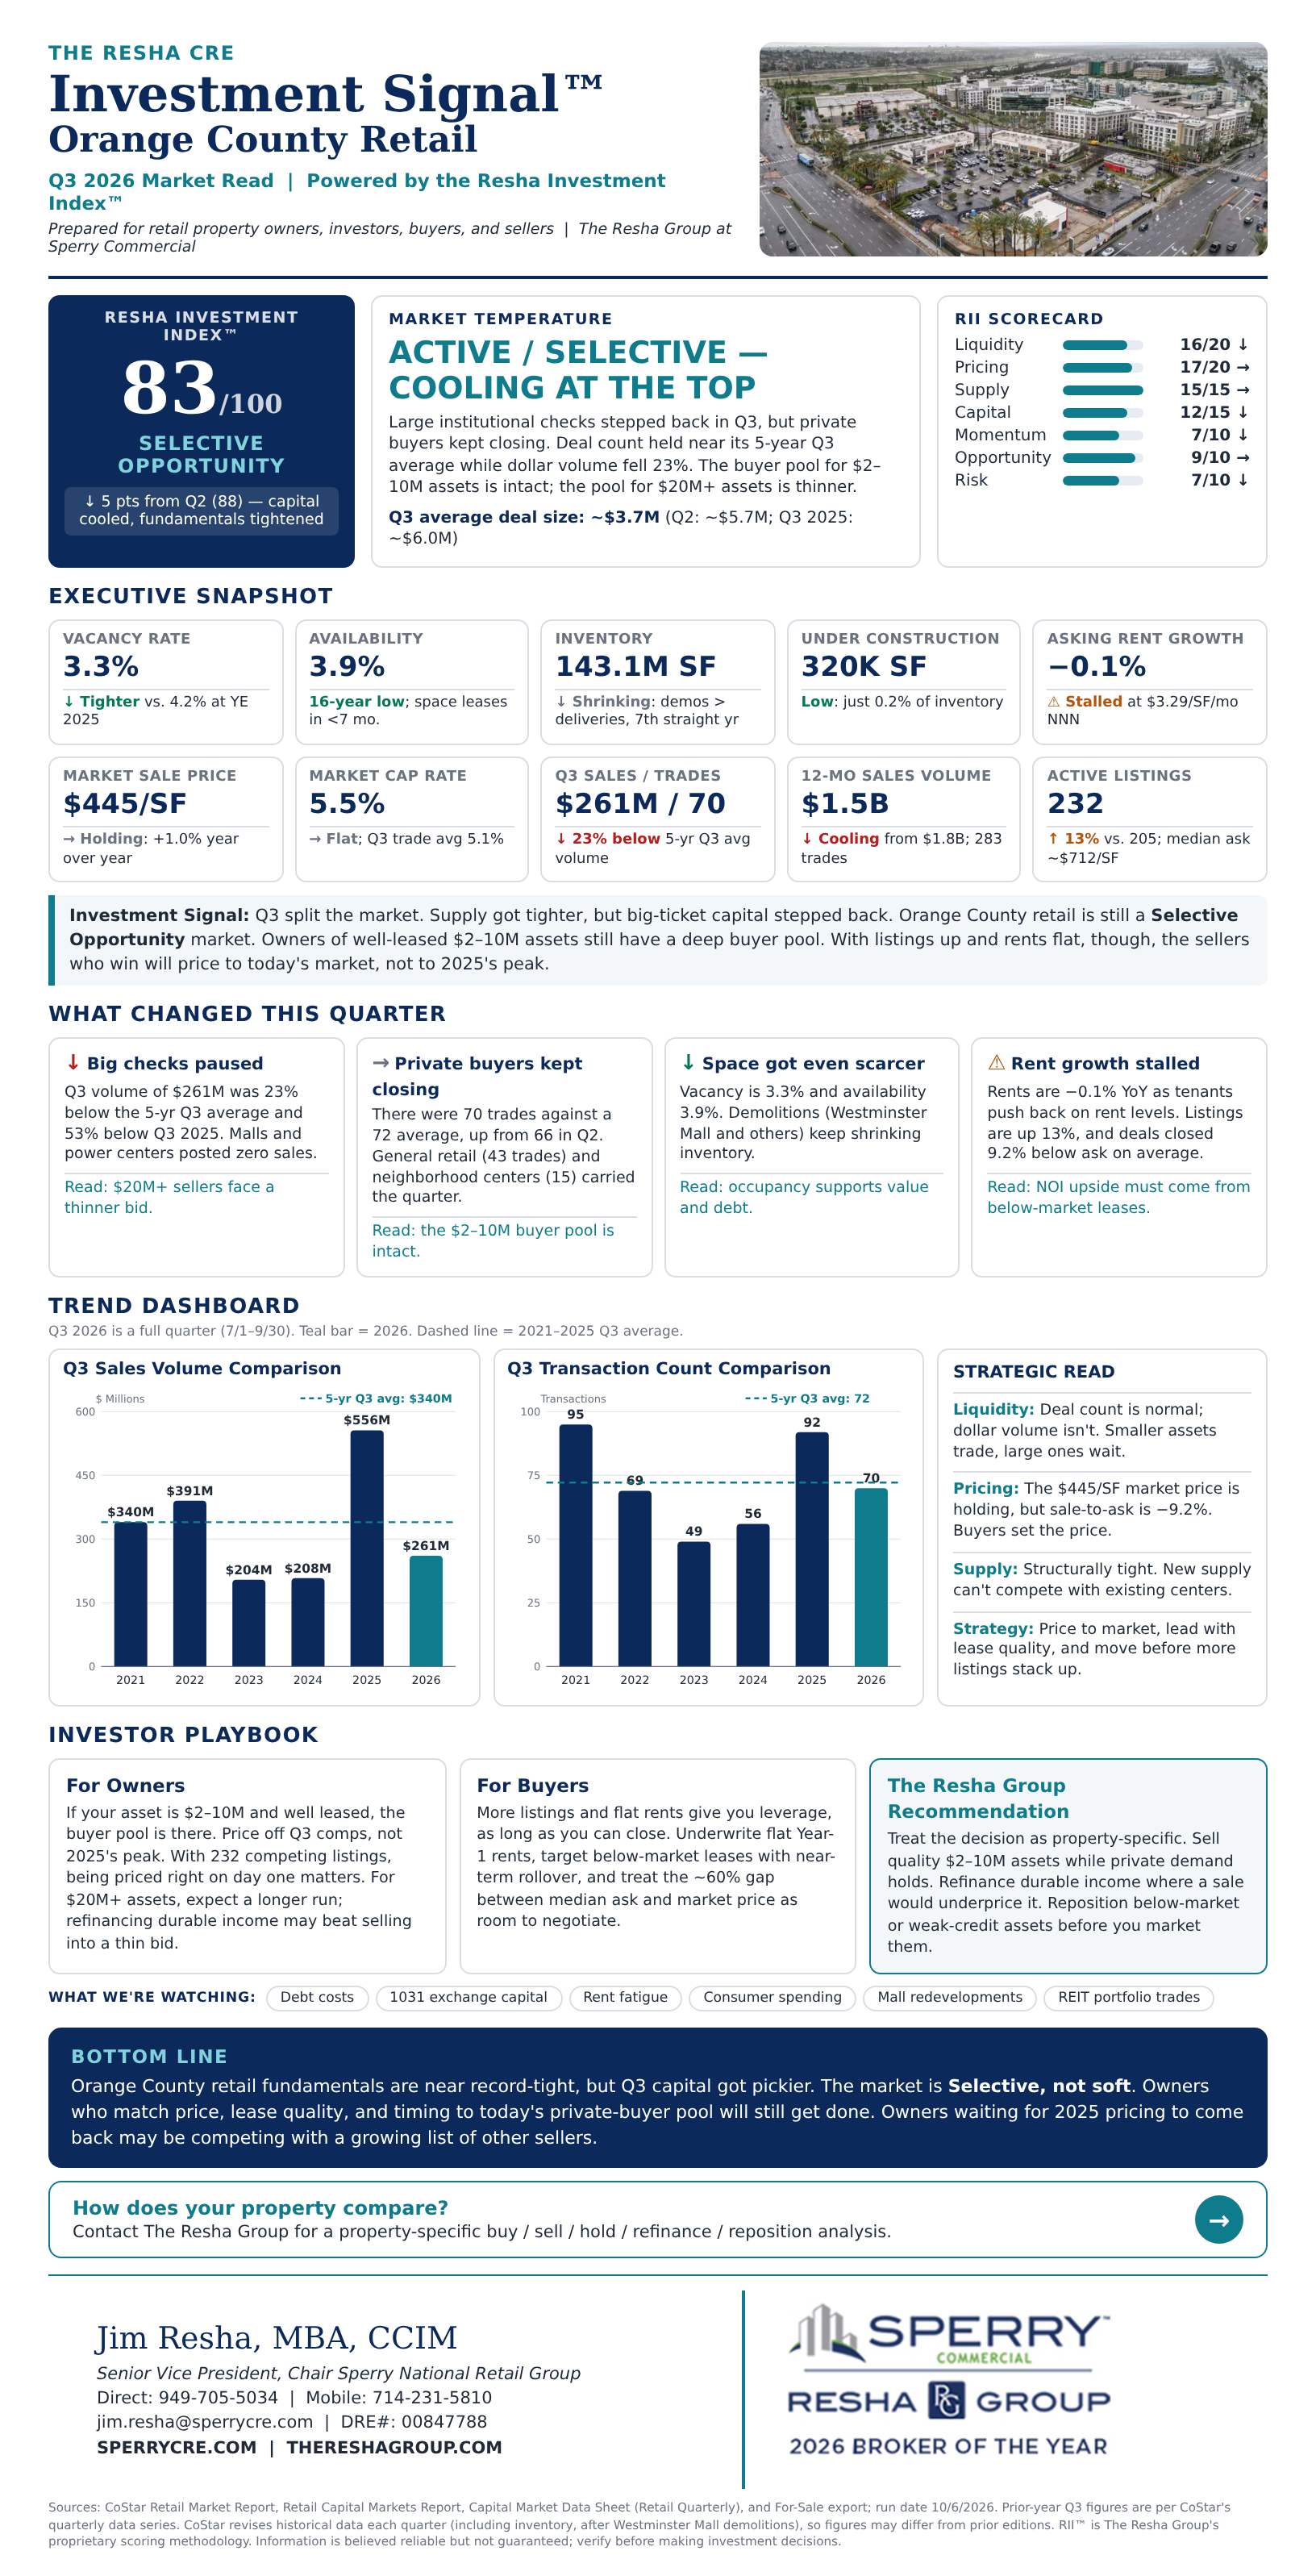
Every quarter we score the Orange County retail market with the Resha Investment Index™. In Q3 it came in at 83 out of 100. That’s still Selective Opportunity, but down five points from Q2. Here’s why, and what it means if you own or are buying retail in Orange County.
Fewer dollars, same number of deals
Retail sales in Orange County totaled $261 million in the third quarter, according to CoStar. That’s 23% below the five-year Q3 average of about $340 million, and roughly half of last year’s Q3. On its face, that looks like a slowdown.
Look at the deal count, though. Seventy properties sold, almost exactly the five-year average of 72 and up from 63 in Q2. The average sale fell to about $3.7 million, from roughly $5.8 million the quarter before.
What happened is simple. The large institutional trades that drove 2025’s record year paused. Malls and power centers posted no sales at all. The private buyers who buy $2–10 million neighborhood centers, strip centers and single-tenant buildings kept closing. So far this year, private buyers account for about 62% of retail dollars traded in the county.
Space has rarely been tighter
Vacancy is 3.3%, and availability is 3.9%, a 16-year low. Good space leases in under seven months. Construction totals about 320,000 square feet, just 0.2% of inventory, and demolitions have outpaced new deliveries for seven straight years as old malls and big boxes turn into housing. Orange County is shrinking its retail supply.
But rents have gone flat
Asking rents were down 0.1% over the past year after a decade of steady gains. Tenants are filling space, but they are pushing back on price. For owners, that means rent growth now comes from leases that are below market today, not from the market lifting everyone.
More competition for sellers
There are 232 retail properties listed for sale, up 13% from last quarter. The median asking price is about $712 per square foot, against a CoStar market price of $445. Properties are selling about 9% below asking on average. Sellers who price to 2025’s peak are competing with a growing list.
What we would do now
Owners of well-leased $2–10M assets: the buyer pool is intact. If a sale, exchange or estate move is likely in the next 12–24 months, test the market priced off Q3 comps.
Owners of $20M+ assets: expect a thinner bid and a longer marketing period. Refinancing durable income may beat selling right now.
Owners with below-market leases or weak credit: reposition before you sell. The upside is in your rent roll.
Buyers: you have more choice and more leverage than a year ago. Underwrite flat first-year rents and focus on leases with near-term mark-to-market.
Every property is different. If you want to know how yours compares, contact The Resha Group for a property-specific buy, sell, hold, refinance or reposition analysis.
Full Signal: