Is Your Property Ready for its Next Loan?
By Jim Resha, MBA, CCIM — The Resha Group at Sperry Commercial
The most important real estate news this week isn't a property sale. It's debt.
Orange County Retail Is About as Tight as It Gets
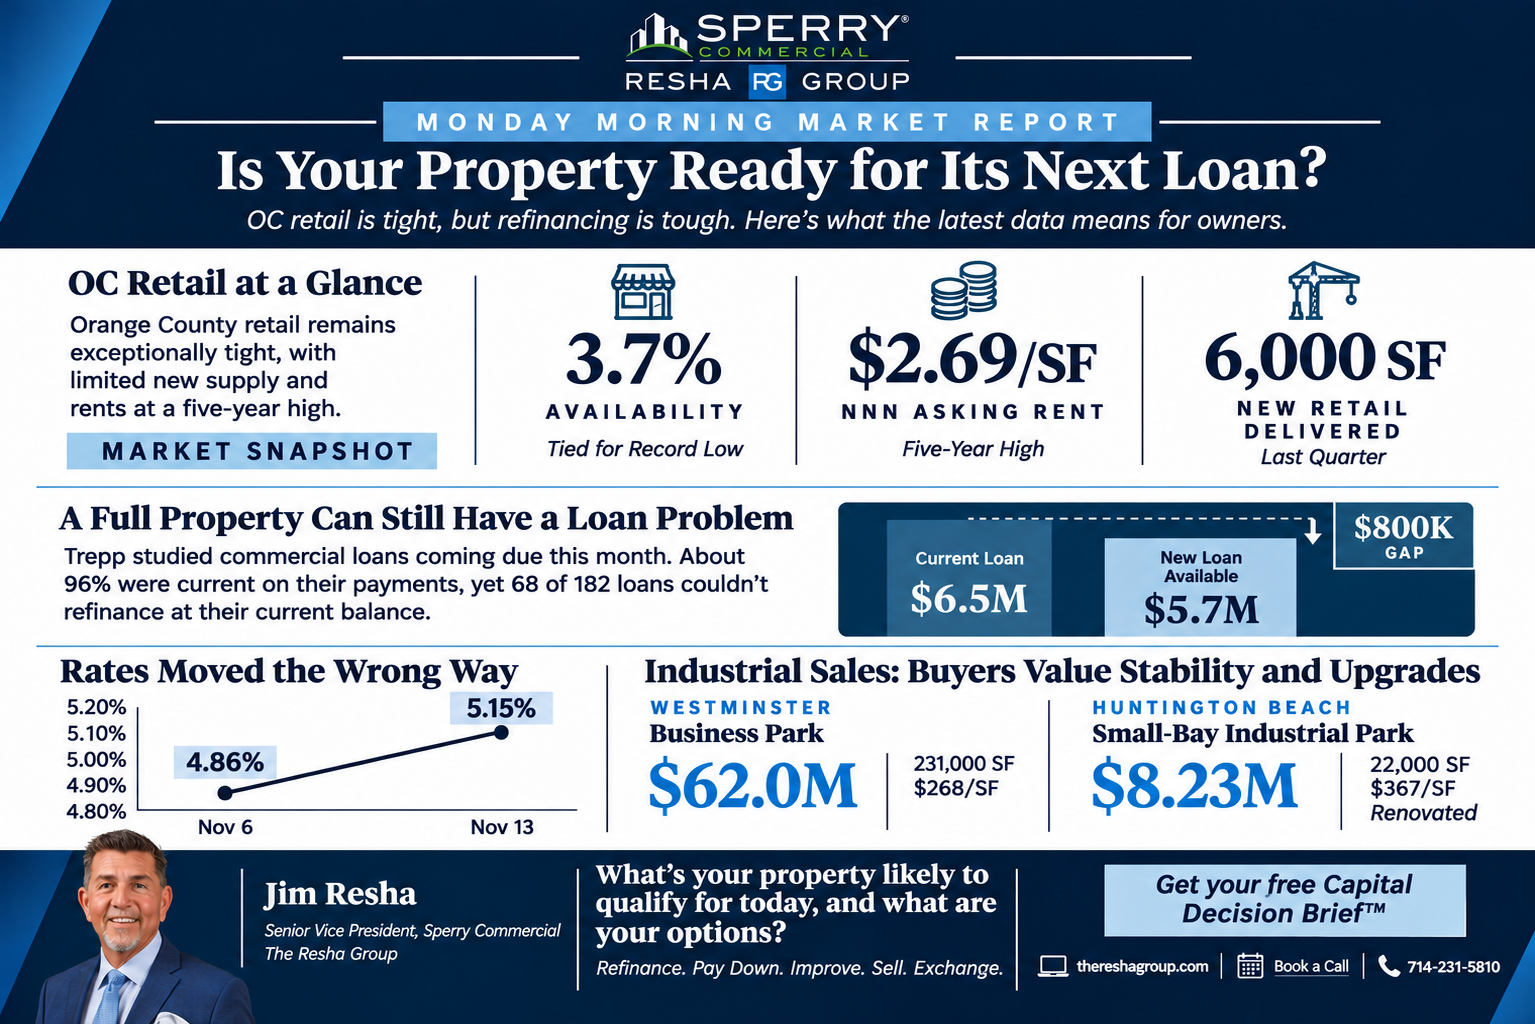
CBRE's latest quarterly data puts OC retail availability at 3.7%, tied for the lowest on record. Average asking rents hit $2.69 per square foot (NNN), a five-year high. Only 6,000 square feet of new retail was delivered countywide last quarter.
Demand isn't the problem; the problem is there's almost no space to lease.
A recent example: Peninsula Marketplace in Huntington Beach, a Ralphs-anchored center about 99% leased, sold for roughly $56 million in October.
A Full Property Can Still Have a Loan Problem
Trepp studied commercial loans coming due this month. About 96% were current on their payments, yet 68 of 182 loans couldn't refinance at their current balance.
Lenders now want more income cushion at higher rates. Most of those borrowers did nothing wrong. Their properties simply qualify for a smaller loan than they have today.
Here's how that works on a hypothetical OC retail center:
Net income: $600,000 a year
Current loan balance: $6.5 million
New loan: about 6.75%, with lenders requiring 1.35x coverage — roughly $5.7 million
Refinance gap: The owner would need to bring about $800,000 to refinance
Rates Moved the Wrong Way
The 10-year Treasury rose from 4.86% to 5.15% in one week. In the example above, a loan priced half a point higher shrinks by about another $280,000.
Don't plan a refinance around rates falling.
The Good News for Retail: Lender Stress Is Easing
Nationally, the share of retail loans in workout fell last month while hotels and apartments drove the overall increase.
Well-leased neighborhood retail is in a much better position than the headlines suggest.
Industrial Note: What It Means for Retail Owners
Three recent industrial sales point to the same lesson:
In Westminster, a fully leased 231,000 SF business park sold for $62 million (about $268/SF).
In Huntington Beach, a 22,000 SF small-bay park sold for $8.23 million (about $367/SF) after a renovation. It had traded for $5.76 million just two years earlier.
In Corona, a fully leased 117,000 SF building sold for $21.5 million (about $184/SF).
The takeaway for retail owners is the same: buyers pay for stable income and for properties that have been improved.
If your center is tired or under-rented, improving it before a sale or refinance may matter more than the market itself.
What We'd Do Now
Know your number: what your property qualifies for today versus what you owe.
Start 12 to 24 months before your loan matures, not 90 days.
Weigh all your options side by side: refinance, pay down, improve, sell or exchange.
If your loan matures tomorrow, would you be comfortable with the check you might need to write, or would you want to see your other options?
We'll run the numbers for you in a free Capital Decision Brief™.
Schedule a meeting with Jim Resha or contact the Resha Group.
*This material is general market information, not investment, tax or legal advice. The example above is hypothetical. Consult your own advisors before making decisions*
Sources: CBRE, Orange County Retail Figures Q3 2026; Trepp, November 2026 CMBS Maturities; U.S. Department of the Treasury, Daily Treasury Yield Curve Rates, November 2026.